The shift is unmistakable: Nvidia just doubled its revenue and the market sold the news. Shares fell about 3% at one point on November 18 after the chipmaker posted record quarterly sales of $115.8 billion, up 103% year-on-year, and guided for $130 billion in the current period. Investors are no longer asking whether the chips will sell. They are asking who will finance the buyers.
Q3 Results: Demand Remains Explosive
Revenue for the August-October quarter blew past the $109.1 billion consensus compiled by LSEG, exceeding it by more than $6 billion. The data center segment, which now accounts for nearly all sales, surged 110% to $107.6 billion. Adjusted earnings per share came in at $2.68 against a $2.48 estimate. Free cash flow doubled to roughly $44 billion. Interim CEO Colette Kress described the Vera Rubin NVL72 ramp as the fastest product launch in company history, with racks already running at Microsoft Azure, Google Cloud and Oracle Cloud Infrastructure.
Stock Reaction: From Chip Demand to Credit Risk
Despite the clean beat, the stock gave back early after-hours gains and slipped in the regular session. The trend underneath is a rotation of focus. For quarters, the market priced Nvidia on unit demand. Now the debate has moved to the balance sheets of the emerging “neo-cloud” providers — companies like CoreWeave and IREN — that have been borrowing heavily to build out GPU clusters. Both names fell on November 18 alongside Nvidia.
Neo-Cloud Exposure Contracts
Kress addressed the funding question directly on the earnings call, stating the company will be selective about which emerging cloud providers it supports financially. The numbers show Nvidia is already pulling back. Maximum contractual liability to neo-clouds — triggered when a customer secures financing, equipment is delivered and accepted — dropped from $36 billion at the end of July to $32 billion at the end of October. That $4 billion reduction in three months is what’s changing: the supplier is capping its own credit risk even as end-user demand accelerates.
Leadership Transition: Huang Exit Confirmed
This was the first report since founder Jensen Huang resigned on November 12 following a board investigation into a disclosed relationship with a business executive accused of being a Chinese spy. Board Chairman Harvey Jones told analysts there are no plans to bring Huang back. Kress, who remains CFO, is steering the ship while an independent board committee continues its review and a search for a permanent CEO gets underway. The risk language in the filing highlights the leadership transition and the ongoing investigation as material uncertainties.
Guidance: Higher Revenue, Lower Margins
Fourth-quarter revenue is guided to $130 billion, plus or minus 3%, well above the $125 billion street view. The quarter includes an extra week and assumes no data center compute sales to China. Gross margins are guided to 71%-72%, down from roughly 75% in Q3. Nvidia returned about $28 billion to shareholders in the quarter and has roughly $227 billion remaining under its buyback authorization after the board added $150 billion in September.
Watch This Space
The Vera Rubin ramp is live at the major hyperscalers. Meta has signaled a wider rollout. Nvidia has also expanded Anthropic’s access to Grace Blackwell and Vera Rubin capacity through cloud partners and pointed to an agreement to acquire Hugging Face. The next earnings call will show whether the neo-cloud funding gate stays tight or reopens.
Sources
- Nvidia stock falls 3% at one point despite doubling revenue; focus is on funding for emerging clouds|Purimagic | 横断AIニュース
- Nvidia (price up) tops forecasts by $7 billion as Kress steers first report since Huang exit
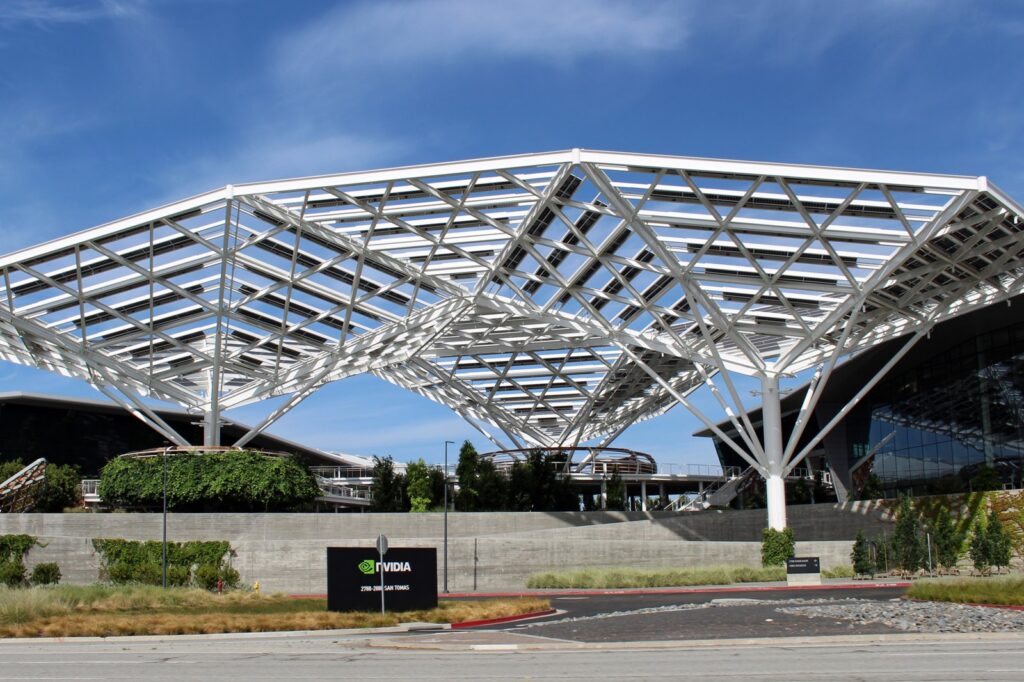
Photo: Coolcaesar (CC BY-SA 4.0)